What Is an NBFC? Meaning, Types & How It Works
Your plain-English guide to India's non-banking lenders: what they do, how they differ from banks and how to pick a safe one.
SHORT ANSWER
An NBFC (non-banking financial company) is an RBI-regulated company that gives loans and other financial services like a bank, but does not hold a banking licence or accept demand deposits.
Regulator
Reserve Bank of India
Governed by
Companies Act and RBI Act, 1934
Can do
Lend, finance assets, invest
Cannot do
Accept demand deposits
Insurance
No deposit insurance cover
If you have been turned down by a bank or just want a quicker loan, you have probably seen the question: what is an NBFC? In India, NBFCs fund everything from two-wheelers and gold loans to small business credit. This guide explains how they work, the main types, and what to check before you borrow or build one.
What Is an NBFC? Meaning in Simple Words
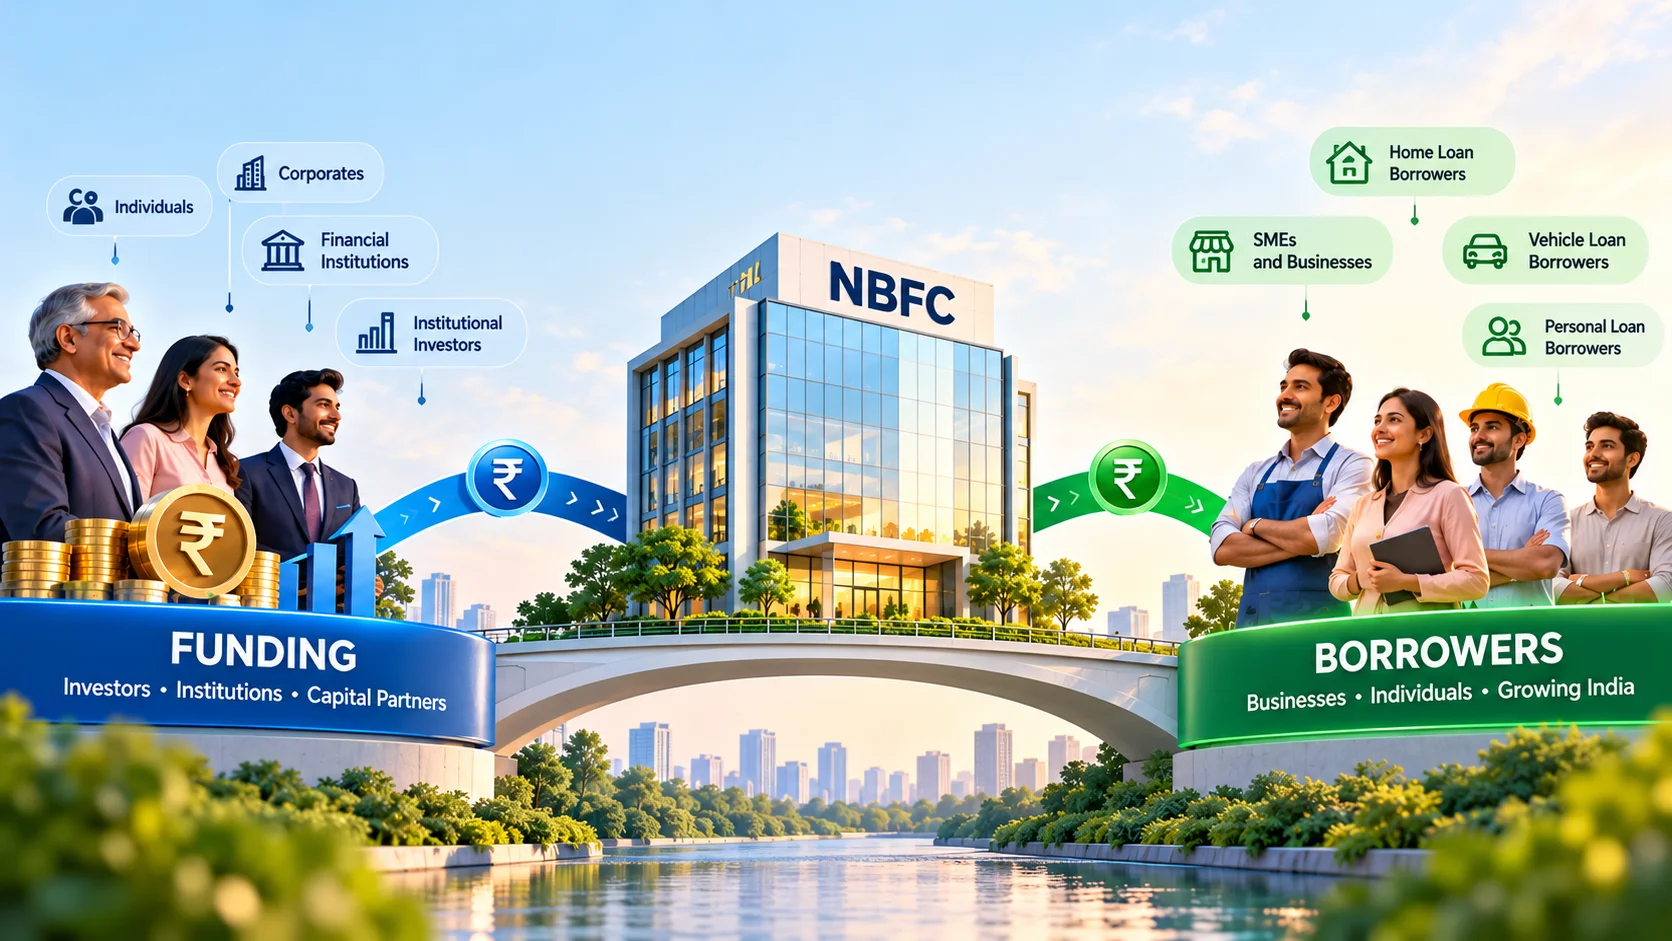
An NBFC is a company registered under the Companies Act and regulated by the Reserve Bank of India (RBI). It lends, finances assets and invests, much like a bank. The key difference is the licence. NBFCs cannot accept demand deposits and are not part of the payment and settlement system.
Why NBFCs matter
How Does an NBFC Work?
Raise funds
From banks, debentures and investors.
Assess
Check KYC, income and credit history.
Lend
Disburse the loan to the borrower.
Collect
Earn interest; repay funders.
Income comes from the spread between what the NBFC pays for funds and what it charges borrowers. Modern NBFCs run this on loan management software or a complete NBFC software suite, using digital checks like Aadhaar and PAN verification and CIBIL credit reports. Repayments often use E-NACH mandates.
Types of NBFC in India
RBI classifies NBFCs by activity. Filter to explore.
Lending
Asset Finance Company
Finances physical assets like vehicles and machinery.
Loan Company
Provides loans for purposes other than asset finance, such as personal and gold loans.
Investment
Investment Company
Deals mainly in securities such as shares and bonds.
Core Investment Company
Holds investments in group companies.
Specialized
Infrastructure Finance Company
Funds roads, power, ports and other infrastructure.
NBFC-MFI
Gives small loans to low-income households. See microfinance software.
NBFC-Factor
Buys receivables to give businesses quick working capital.
P2P and Account Aggregator
Platform models: peer-to-peer lending and consent-based data sharing.
RBI also uses scale-based regulation, grouping NBFCs into layers by size and risk, so larger players face tighter rules.
NBFC vs Bank: Key Differences
| Feature | NBFC | Bank |
|---|---|---|
| Regulator | RBI (RBI Act, Companies Act) | RBI (Banking Regulation Act) |
| Demand deposits | Not allowed | Allowed |
| Deposit insurance | Not available | Available up to the DICGC limit |
| CRR/SLR | Not required | Required |
| Approval speed | Often faster, flexible | Often more documentation |
| Focus | Niche and underserved segments | Full banking services |
How to Choose a Safe NBFC Loan Provider
Do
Verify RBI registration
Compare interest and total cost
Read the key fact statement
Avoid
Hidden fees and vague terms
Apps with no registered partner
Sharing OTPs or documents carelessly
Pro tip: search the lender's name in the list of registered NBFCs on the RBI website before you apply.
Thinking of Starting or Partnering With an NBFC?
Founders have three routes: NBFC registration, an NBFC takeover, or partnering with an existing NBFC through NBFC collaboration or co-lending. Read more in our guides on fintech and NBFC partnerships, lenders and NBFC collaboration and MFIs and NBFC collaboration. A reliable stack also needs payouts, payment gateway and core banking solutions.
Frequently Asked Questions
Summary and Conclusion
So, what is an NBFC? It is an RBI-regulated lender that fills gaps banks leave, with faster, more specialised credit. Borrowers should verify registration and compare costs. Founders should choose registration, takeover or partnership, and build on compliant technology.