BNPL Software: How to Choose the Best Buy Now, Pay Later Solution for Your Business
How BNPL works, what it costs, who the leading providers are and how to launch it without the usual risks.
BNPL software is the platform that lets banks, lenders and merchants offer instalment payments at checkout. The best BNPL solution fits your regulatory model, approves customers in seconds, automates repayments and connects to your payments and lending stack.
Choosing BNPL software is now a core payments decision. Shoppers abandon big baskets at checkout, and lenders want new short-term credit products without long build cycles. This guide answers the key questions: what BNPL is, how it works, what it costs, which providers to consider, how the architecture and technology fit together, and how to set it up.
What Is Buy Now, Pay Later (BNPL)?
Definition. Buy now, pay later is short-term financing at checkout. The customer receives the purchase now and repays in scheduled instalments, while the merchant is paid upfront by a lender.
BNPL software is the technology behind it: checkout widgets, instant decisioning, loan management, collections and reporting. In India, credit at checkout is generally extended by regulated lenders such as banks and NBFCs, directly or with fintech partners. Read current rules on the RBI website.
How Do Buy Now, Pay Later Services Work?
Choose
Customer selects BNPL at checkout.
Approve
Instant KYC and credit check.
Pay Merchant
Lender pays the merchant upfront.
Repay
Customer repays in instalments.
What Are the Benefits of Buy Now, Pay Later?
For Businesses
Higher conversion at checkout
Larger basket sizes
Upfront settlement
For Customers
Flexible, predictable payments
Quick, paperless approval
Access to higher-value purchases
For Banks & Lenders
New short-term credit product
Fresh customer segments
Rich repayment data
Why Use BNPL Payment Methods for Your Business?
Do Customers or Businesses Pay More With BNPL?
It depends on the plan and the provider. Merchants usually pay a fee per transaction. Customers often pay no interest on short plans when they repay on time, but longer plans and late payments can carry interest or fees.
| Party | Typical Cost | What offsets it |
|---|---|---|
| Business | Fee per BNPL transaction | Higher conversion and basket size, upfront payout |
| Customer | Usually none on short plans if paid on time; possible interest or late fees | Spreading cost over time |
| Lender | Credit and collection risk | Fees, interest and repeat usage |
Best Installment Payments and BNPL Software Providers for Banks and Lenders
These providers appear in BNPL software comparisons. We list AOPAY first because it is our own platform; the others follow alphabetically. Fit depends on your regulatory model, size and budget, so always test with a demo.
AOPAY Technology: BNPL Ready Payments & Lending Stack
AOPAY lets banks, NBFCs, fintechs and merchants combine instalment payments with payments, lending and verification on one platform.
Payment collection across cards, UPI, wallets, net banking and BNPL options
White-label checkout and payment links with BNPL integration
Smart payment routing to improve success rates
Loan management for the instalment lifecycle
Co-lending for bank, NBFC and fintech funding
KYC verification, e-mandates, payouts, virtual accounts and escrow
| Provider | Known for |
|---|---|
| Fiserv | BNPL processing for financial institutions, with credit evaluation, fraud prevention and structured payments. |
| HES Fintech | BNPL loan software for pay-in-4, deferred billing, longer instalments and B2B plans, with white-label options. |
| M2P Fintech | BNPL lending with origination and loan management, merchant onboarding and multi-channel access. |
| TimveroOS | Configurable BNPL building platform for pay-in-4, pay-monthly and B2B trade credit, extendable through an SDK. |
How Can AOPAY Help?
AOPAY covers the BNPL value chain, so you do not stitch together many vendors:
Checkout and collections: payment gateway and payment links with BNPL options.
Identity and credit: Aadhaar, PAN, bank account checks and credit bureau reports.
Repayments and payouts: e-mandates and instant payouts.
Money control: virtual accounts, escrow accounts and treasury management.
Lending backbone: loan management, NBFC software, co-lending and core banking solutions.
Need a regulated lending partner? Our NBFC collaboration advisory can help.
Related: Payday Lenders and NBFC Collaboration.
BNPL System Architecture
Checkout Layer
Online checkout, point of sale, payment links and merchant portal.
Integration Layer
Open integrations to merchants, payment rails, verification and bureau services.
Decision & Loan Engines
KYC, scoring, limits, plan configuration, ledger and servicing.
Payments & Collections
Settlement to merchants, e-mandates, reminders and retries.
Data & Infrastructure
Reporting, audit trails, security and cloud or on-premise hosting.
BNPL Software Application Technology
| Technology | Why it matters |
|---|---|
| Real-time decisioning engine | Approvals in seconds at checkout |
| Configurable plan and workflow engine | Launch pay-in-4, instalments or B2B plans without code |
| Open integration interfaces | Connect merchants, KYC, bureaus and payments |
| Fraud and risk controls | Limits, velocity checks and exposure monitoring |
| Automated collections | Mandates, reminders and retry logic cut missed payments |
BNPL Software Market Overview
Published estimates differ by method, so treat numbers as a range. Research firms value India's BNPL market at roughly USD 17 billion to 25 billion in 2025. Most forecasts project growth of about 10% to 13% a year into the early 2030s, after faster growth in the early 2020s.
Drivers: e-commerce growth, digital payments, younger shoppers and bank-led pay-later products.
Challenges: regulation, credit risk and consumer-protection expectations.
Opportunity: embedded and B2B BNPL, and partnerships such as co-lending.
In Europe, BNPL is shaped by consumer-credit rules, PSD2 and GDPR, so check local requirements.
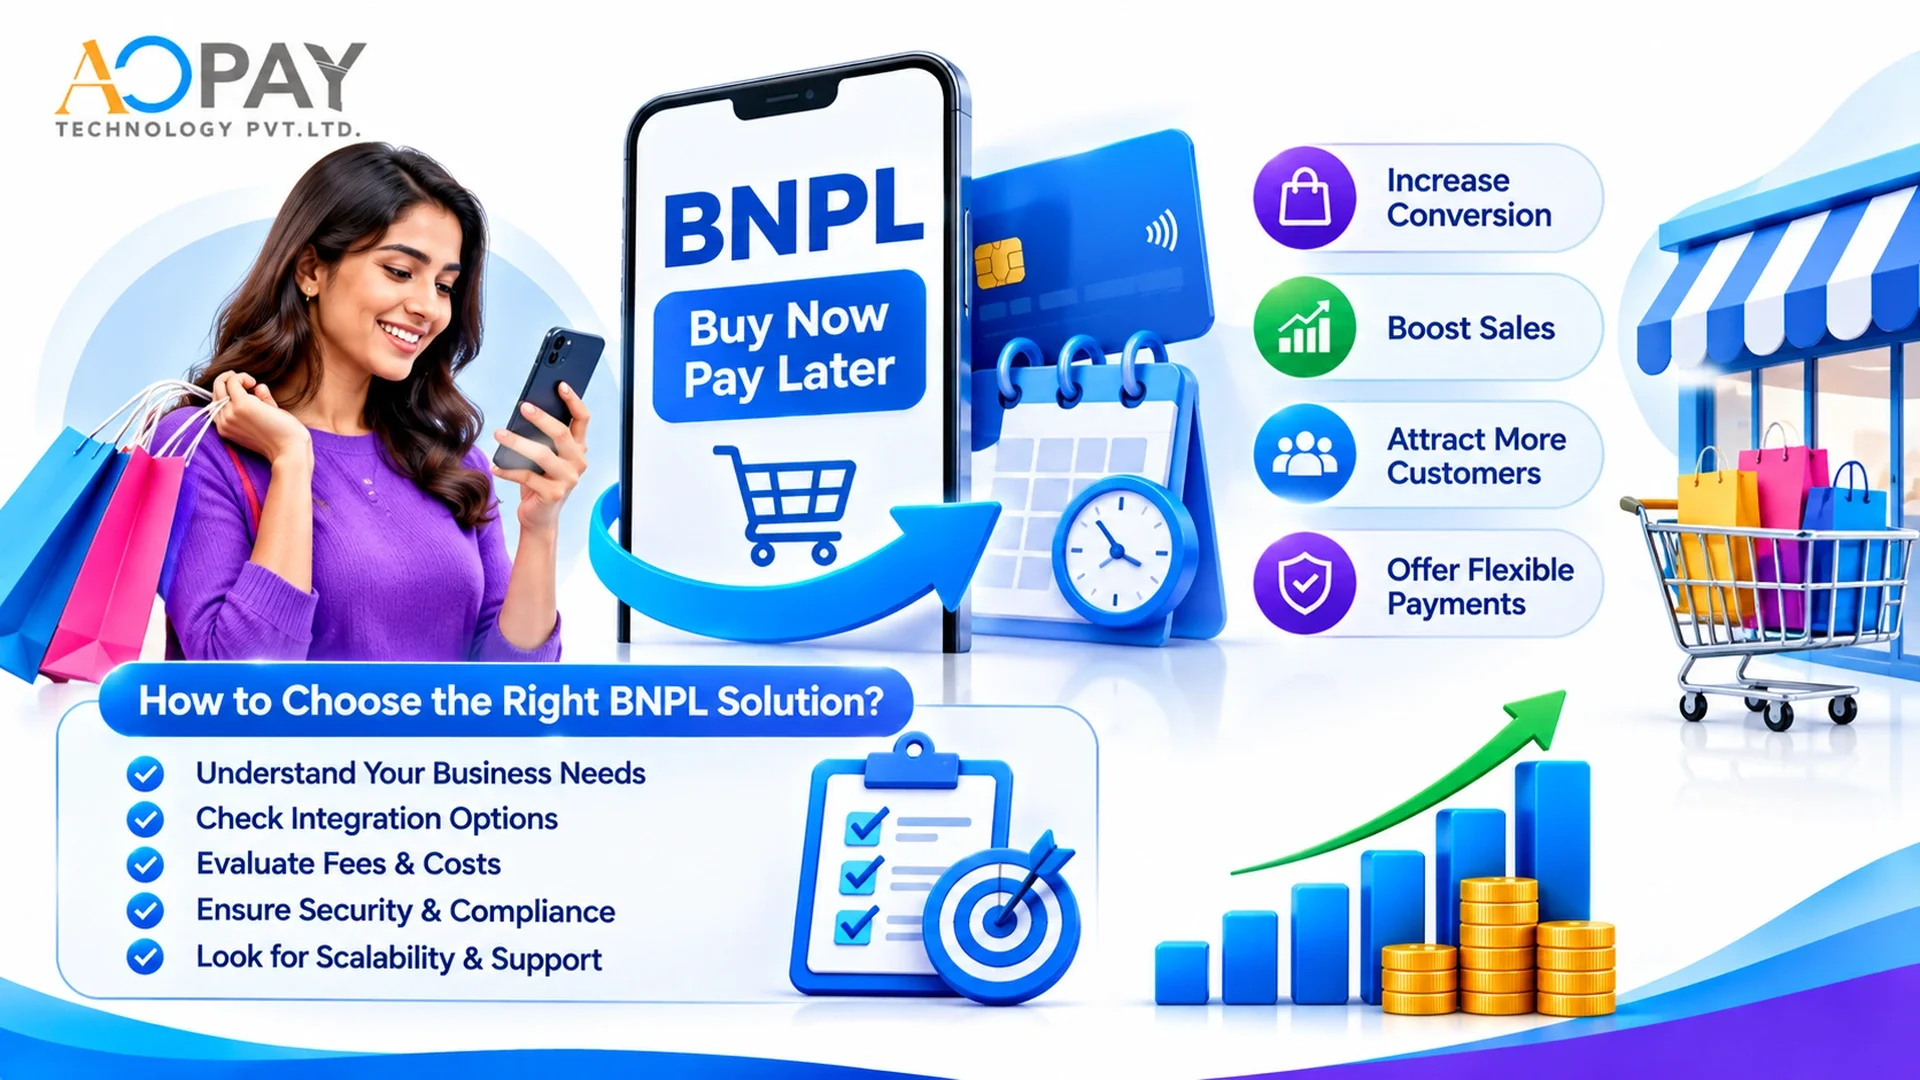
How Do You Choose a Buy Now, Pay Later Provider?
Regulatory fit: works with your licence and lending partner
Plan flexibility: pay-in-4, longer instalments, B2B
Decisioning speed: real-time approval at checkout
Integrations: payments, KYC, bureaus, accounting
Risk controls: limits, fraud checks, early-warning alerts
Reporting and security: audit trails and role-based access
Total cost: pricing model, not just licence fees
Do
Run a pilot with one product
Test your own checkout flow
Avoid
Choosing on features alone
Ignoring collections and risk
How Do I Set Up Buy Now, Pay Later for My Business?
1. Define the product. Choose plan types, ticket sizes and eligible customers.
2. Pick a regulated lending partner. A bank or NBFC funds the credit and carries compliance duties.
3. Choose BNPL software. Cover checkout, decisioning, loan management and collections.
4. Set credit and risk rules. Configure KYC, bureau checks, limits and fraud controls.
5. Integrate checkout and payments. Add BNPL to your checkout and payment links.
6. Automate repayments. Use e-mandates, reminders and retry logic.
7. Pilot, then scale. Review approvals and delinquency before expanding.
Frequently Asked Questions
Best BNPL software matches your regulatory model, approves customers instantly, automates repayments and connects to your payments and lending stack. Start with a clear product, a regulated partner and a pilot. For more, read core banking explained and lenders and NBFC collaboration.
Launch BNPL With AOPAY
Talk to our team about BNPL-ready payments, loan management and co-lending for your bank, NBFC, fintech or business.
Book a DemoExplore Payment Solutions