Best Microfinance Software: Features, Benefits, and How to Choose the Right One
What good microfinance software does, who the leading providers are in India, and a checklist you can build yourself.
The best microfinance software automates client onboarding, group and individual loans, collections, savings and compliance reporting on one secure platform. Choose one that fits your lending model, works in the field and integrates with your existing systems.
Choosing the best microfinance software is a big decision. Paper registers, spreadsheets and disconnected tools slow collections, hide risk and make audits painful. This guide covers features, benefits, leading providers in India, how the software works, its architecture and technology, the market, and how to choose.
Features and Benefits of Microfinance Software
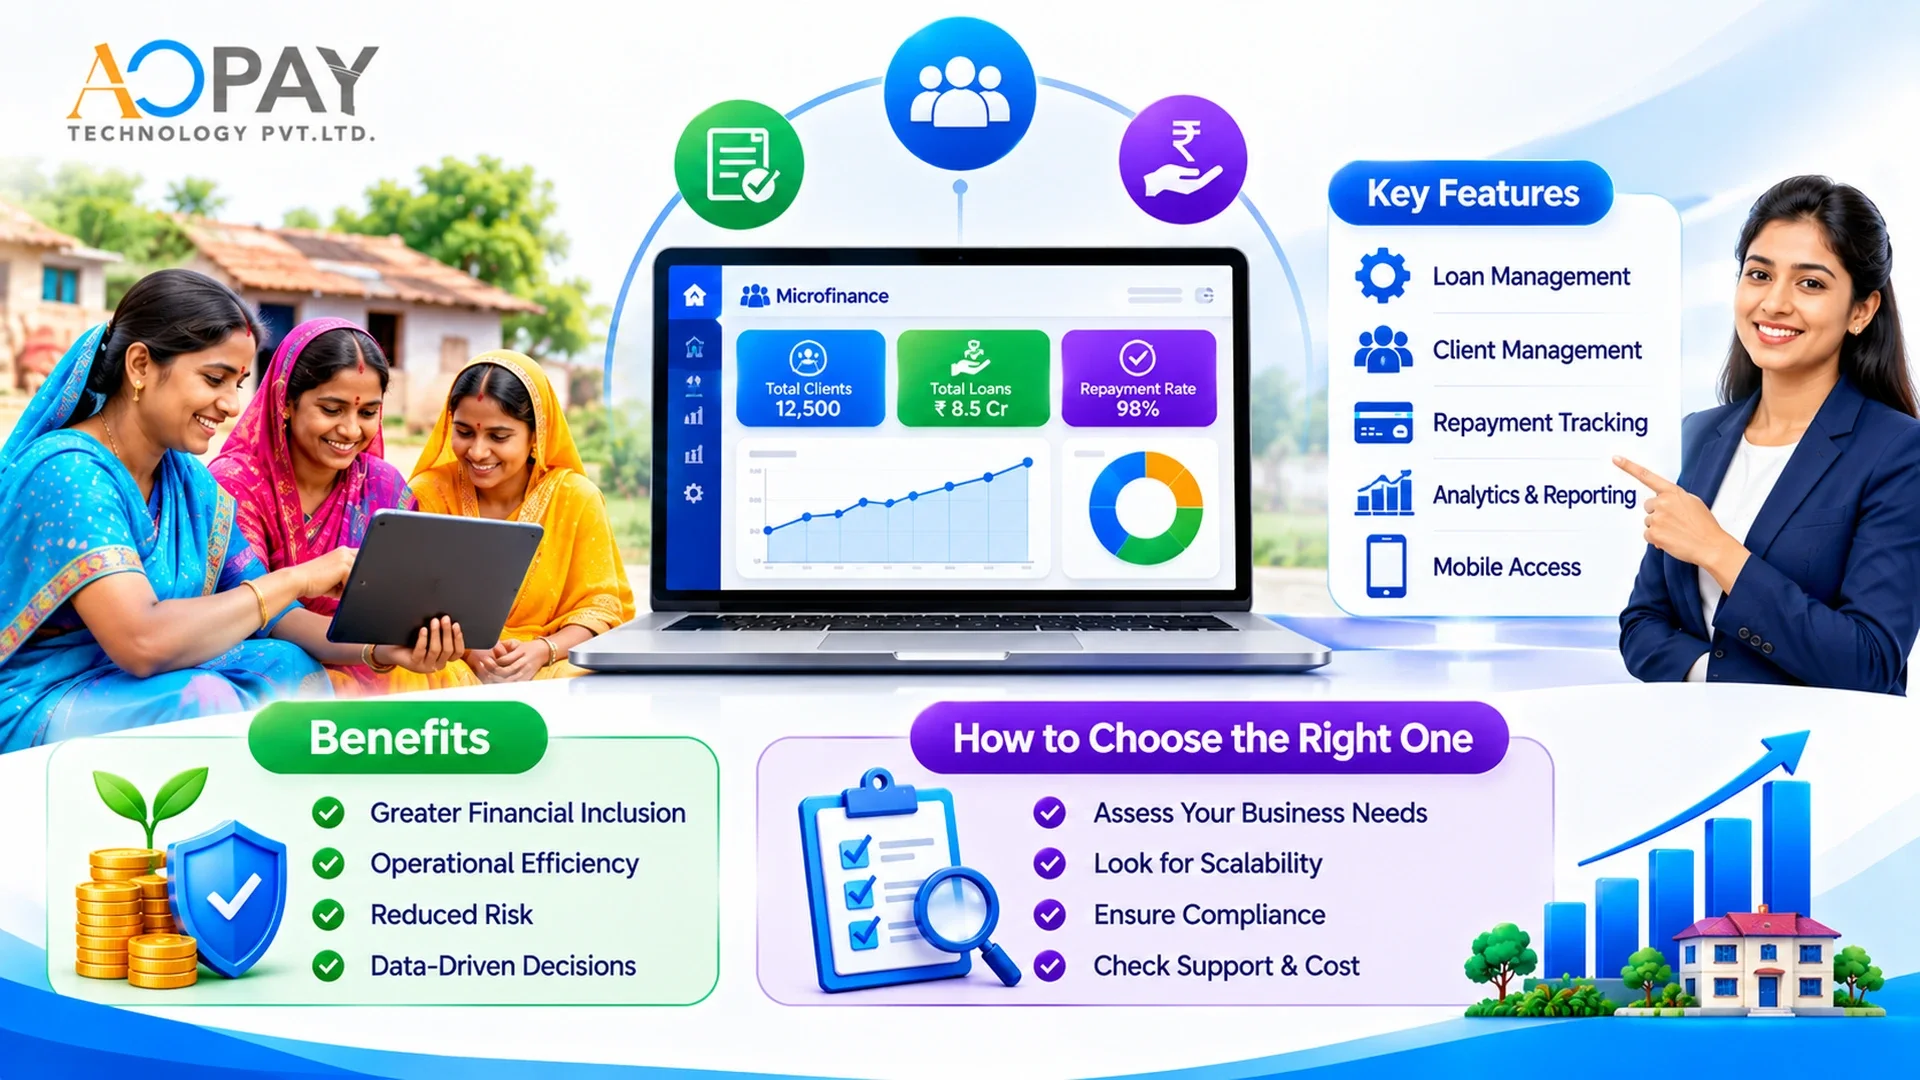
Microfinance software manages the full lending cycle for MFIs, NBFCs and cooperative lenders. These are the features that matter most.
Group & Individual Loans
Manage microloans, SHGs and joint liability groups.
Digital onboarding
KYC with Aadhaar, PAN and bank account checks.
Field Mobile App
Collect and record repayments on site.
Savings Management
Handle savings and deposit products.
Disbursal
Pay out through instant payouts.
Collections
Automate repayments with e-mandates.
Accounting
Ledger and financial reports built in.
Compliance Reports
Audit trails and regulatory reporting.
Benefits: fewer manual errors, faster approvals, real-time portfolio visibility, safer collections and audit-ready records. Credit checks using credit bureau reports also help curb over-indebtedness.
Best Microfinance Software Providers in India
These providers appear in Indian microfinance software comparisons. We list AOPAY first because it is our own platform; the others follow alphabetically. Fit depends on size, regulation and budget, so always test with a demo.
AOPAY Technology: AOPAY MicroFin
A secure microfinance software solution for MFIs, NBFCs, credit cooperatives and NGO-based micro-lenders, built for Indian lending models.
End-to-end loan management for microloans, group and individual lending.
Rural and urban models, including agricultural lending cycles and self-help groups.
Digital onboarding with KYC and paperless loan applications and approvals.
Loan disbursals, repayment tracking and savings account management.
Mobile app suite for field operations.
Financial reporting and compliance, with flexible deployment and integrations.
| Provider | Known for |
|---|---|
| Finflux (M2P Fintech) | Lending platform with integrated origination and loan management, used by Indian NBFCs and MFIs. |
| Mifos X (Apache Fineract) | Open-source microfinance and core banking platform, with lower licence cost and more self-managed effort. |
| Vexil Infotech IMS | Integrated microfinance solution covering loan administration, customer data, accounting and reporting. |
Also see AOPAY's loan management software, NBFC software and core banking solutions.
How Does Microfinance Software Work?
1. Onboard
Capture client data and verify KYC.
2. Form Groups
Create SHGs or individual profiles.
3. Appraise
Check credit and approve digitally.
4. Disburse
Pay funds to the borrower's account.
5. Collect
Record repayments in the field or by mandate.
6. Report
Track portfolio and file compliance reports.
Microfinance System Architecture
A modern microfinance system is layered, so each part can scale and change without breaking the rest.
Channels
Field officer mobile app, branch screens, borrower touchpoints.
Integration Layer
Open integrations to payment gateway, verification and bureau services.
Core Modules
Clients, groups, loans, savings, collections, accounting.
Data & Reporting
Audit trails, dashboards, regulatory and management reports.
Infrastructure
Cloud or on-premise hosting, role-based security, backups.
Microfinance Software Application Technology
| Technology | Why it Matters |
|---|---|
| Cloud-based delivery | Faster rollout, easier updates, scalable capacity. |
| Mobile field applications | Records repayments where they happen. |
| Open integration interfaces | Connects KYC, payments and credit checks. |
| Workflow automation | Faster approvals with fewer manual steps. |
| Role-based security and audit logs | Protects borrower data and supports compliance. |
Microfinance Software Market Overview
India's microfinance sector is among the world's largest financial inclusion ecosystems, and technology now sits at the centre of its operations. Published estimates of the microfinance software market vary widely by research method, so we avoid quoting a single figure. The direction is consistent, though:
Demand is rising as MFIs, NBFCs and cooperatives move off paper and spreadsheets.
Cloud and mobile are becoming the default for deployment and field work.
Partnerships such as co-lending need shared, real-time data. Read about MFIs and NBFC collaboration.
Compliance pressure favours platforms with strong audit trails and reporting.
In Europe, microfinance providers apply the same logic under PSD2 and GDPR.
How to Choose the Right Microfinance Software
Build your own shortlist checklist. Tick what you need, then copy it into your RFP or demo request.
Do
Test your real field workflows in a demo
Check compliance fit for your institution type
Compare total cost, not just licence fees
Avoid
Choosing on brochures alone
Ignoring migration and training effort
Skipping a pilot in one branch
Frequently Asked Questions
The best microfinance software matches your lending model, works in the field, integrates with your stack and keeps you audit-ready. Build your checklist, compare providers through live demos and pilot before you scale. Related reading: core banking explained, credit unions and NBFC collaboration and the co-lending buyer's guide.
Book a Demo of AOPAY Microfinance Software
See AOPAY MicroFin manage onboarding, group lending, collections and reporting for your MFI, NBFC or cooperative.